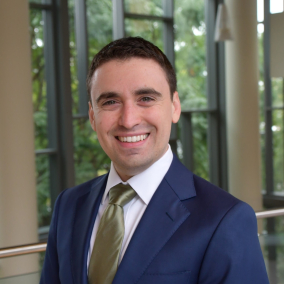
Ian Sapollnik
Job Market Candidate
Research Fields
Public Economics, Financial EconomicsContact Information
Email Address
ian_s@mit.edu
Office
E52-564
Website
isapollnik.github.io
References
Jim Poterba
Nathan Hendren
Antoinette Schoar
Crisis Relief Through the Tax Code: Effects of Corporate Loss Refunds on Firms and Workers, with Dustin Swonder
Abstract: Governments spend heavily to keep firms alive in crises, yet the corporate income tax works against them: profits are taxed immediately, while losses are relieved only later, and not at all if the firm exits. Tax loss carrybacks narrow this asymmetry by refunding taxes paid on prior-year profits, and because eligibility depends on years already closed, firms cannot manipulate it. We study Australia's 2020 carryback using the universe of business tax returns linked to monthly payroll records. Refunds reached larger firms with persistent profit histories, and conditional on entitlement, more financially constrained firms were more likely to claim. Comparing corporations to matched pass-through entities, which were statutorily excluded, we find that the average refund raised two-year survival by 0.25 percentage points. Each dollar of entitlement raised cumulative payroll by 77 cents over sixteen months, mainly through retention of incumbent workers, with no detectable change in pay per employee. Following workers across employers, roughly 30 percent of this response appears as higher earnings; the rest would have been earned elsewhere. Using pre-policy loss cohorts, we estimate that 52 cents of each refunded dollar would have been deducted within seven years.
Publications
Tax Policy and Business Entry, with Dustin Swonder
Journal of Public Economics, Vol. 252 (Dec 2025): 105537
Abstract: This paper measures the effects of state corporate and personal income tax reforms on business entry using an event study research design. We focus on reforms that do not coincide with federal tax changes, are preceded and followed by stable tax policy, and substantially change tax burdens. Corporate tax reforms cause meaningful changes in business entry: we measure a 5-year elasticity of 2.7 with respect to the net-of-tax rate. This is driven by large effects of tax cuts. Corporate tax cuts also reduce the predicted growth potential of entrants. We do not find strong evidence of cross-border spillovers, and find no evidence that personal income tax reforms affect business entry.
Working Papers
The Emergence of Silicon Valleys: A Role for Government, with Adair Morse and Ofer Eldar
Homeownership and Liquidity: Evidence from a California Lottery, with Dustin Swonder
Fellowships and Awards
2021
- 2025
Doctoral Fellowship, Social Sciences and Humanities Research Council of Canada
2022
C. Lowell Harriss Dissertation Fellowship, Lincoln Institute
2019
Best Undergraduate Research Paper, Canadian Economics Association
2019
Joseph A. Crumb Prize in Economics, UBC